Home › Guides › Example CCI product summary
Example CCI product summary
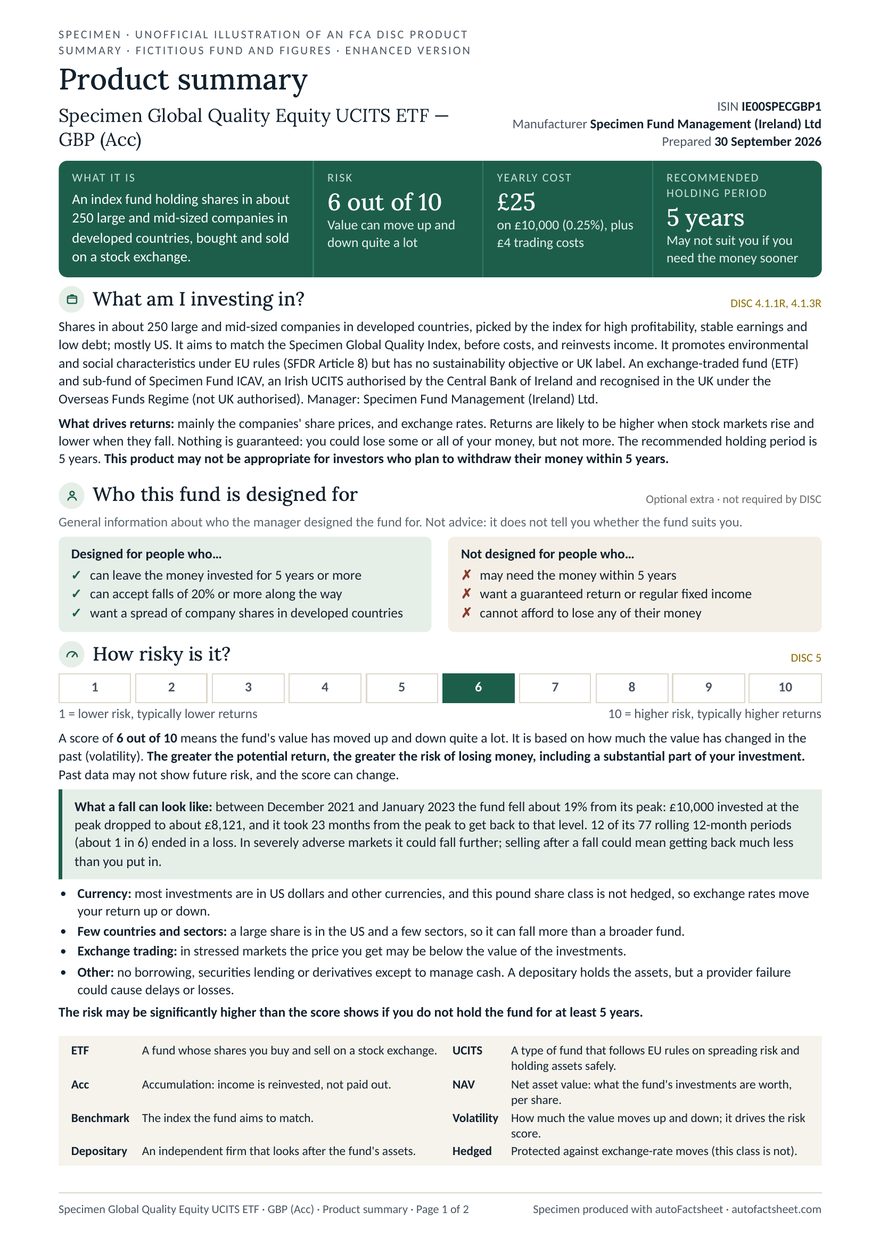
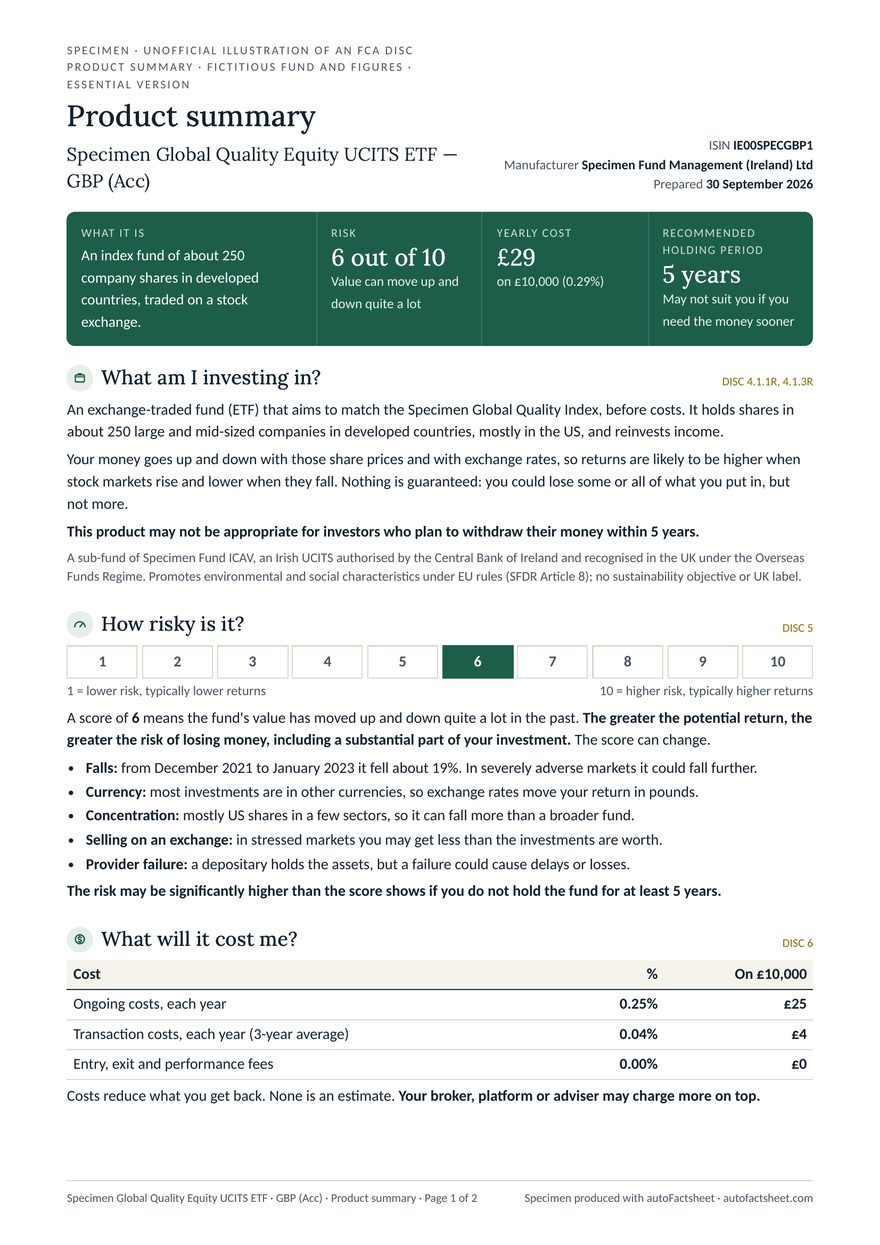
From 8 June 2027, consumer composite investments (CCIs) sold to UK retail investors, including funds, must have a product summary under the FCA's CCI regime, replacing the UCITS KIID and PRIIPs KID. Our example comes in two versions for the same UCITS ETF: Essential, with just what the rules require, and Enhanced, with extras that help investors understand it.
Looking for a CCI product summary template? The FCA has not published one: its policy statement PS25/20 gives firms considerable freedom over design and standardises only the content that must be included. This example shows how the DISC rules can be applied in practice.
Illustrative mock-up only. The FCA does not prescribe a template for CCI product summaries: each one must be designed for the product, meet the DISC rules, be signed off internally and comply with the financial promotion rules, including approval by an FCA-authorised firm where needed. The fund, firms and all figures in this example are fictitious. It is not regulatory advice.
Building your own? Use our CCI product summary checklist, which sets out what the DISC rules require, section by section.
Key dates
| Date | What happens |
|---|---|
| 6 April 2026 | The FCA's CCI rules (the DISC sourcebook) took effect. Firms may switch to product summaries from this date. |
| 6 April 2026 to 7 June 2027 | Transition: firms, including managers of recognised overseas (OFR) funds, can keep using their existing UCITS KIID or PRIIPs KID. |
| 8 June 2027 | Product summaries become mandatory for CCIs sold to UK retail investors. |
Plan for an earlier date: industry discussion suggests some distributors may ask for product summaries from around mid-February 2027, ahead of the FCA deadline (Simmons & Simmons, April 2026).
Two versions: Essential and Enhanced
Essential
Everything the DISC rules require, in short plain sentences. About 900 words over two pages. For firms that want the minimum done cleanly.
Enhanced
The same required content plus optional extras, such as who the fund is designed for, its biggest past fall, good and bad years, and a jargon buster. About 1,400 words. For firms that want to show Consumer Duty effort.
Both use the same fictitious fund and figures, and both keep the at-a-glance tiles: risk score, yearly cost in pounds and recommended holding period.
What the example includes
Each section of the PDF carries a small tag naming the rule it meets. Sections the rules do not require are tagged as optional extras.
| Section | What it shows | FCA rules |
|---|---|---|
| What am I investing in? | Type, objective and strategy, what drives returns, how you could lose money, the recommended holding period and the holding-period warning | DISC 4 |
| How risky is it? | A 1–10 score on a horizontal scale, what it means, severely adverse markets, currency, concentration and other risks | DISC 5 |
| What will it cost me? | Entry, exit, ongoing and transaction costs as a percentage and in pounds on £10,000, performance fees, and why costs matter | DISC 6 |
| What could I have got back? | What £10,000 would have grown to, net of costs, with the benchmark and the required warnings | DISC 7 |
| How do I sell? and If things go wrong | How to sell, how to complain, and the Financial Ombudsman and FSCS position for an overseas fund | DISC 4, COBS 4.15 |
Optional extras in the Enhanced version, not required by DISC
The FCA wants product summaries that people actually read, and its policy statement PS25/20 leaves firms free to design them. The Enhanced version adds:
- "Who this fund is designed for", a plain-English summary of the target market. It is general information, not advice.
- "What a fall can look like", the fund's biggest past fall from peak, how long it took to recover, and how often a 12-month period ended in a loss.
- Good and bad calendar years as a small bar chart.
- A to-scale picture of costs over the recommended holding period.
- A jargon buster for terms such as ETF, NAV and volatility.
- A placeholder for an own-amount link, which a platform or broker could offer (PS25/20 para 6.2).
How the 1–10 risk score works
The score is based on annualised volatility over 10 years, using weekly prices where available. If a product has less than 10 years of history, the missing years must be simulated, or an appropriate benchmark used only if simulation is not possible. The volatility then maps to a score:
| Score | Annualised volatility | Score | Annualised volatility |
|---|---|---|---|
| 1 | under 0.5% | 6 | 12% to under 16% |
| 2 | 0.5% to under 2% | 7 | 16% to under 20% |
| 3 | 2% to under 5% | 8 | 20% to under 30% |
| 4 | 5% to under 9% | 9 | 30% to under 50% |
| 5 | 9% to under 12% | 10 | 50% and over |
The manufacturer must then check that the score fairly reflects the product's risks and adjust it if not. Some products have set or minimum scores: at least 9 for contracts for difference, derivatives, contingent convertibles, VCT and EIS investments and products with under 5 years of volatility record; 10 where you could lose more than you invest; and 1 for structured deposits. Products that cannot readily be sold add 1 to their score. Based on typical volatility, global equity funds are likely to score 6 or 7, compared with typically 4 on the PRIIPs KID scale and 5 or 6 on the UCITS KIID scale.
To keep the example simple, its score is worked out from monthly prices since the fictitious fund's launch, and the PDF says so. A real product summary must follow the full method above.
Required statements and updates
- Titled "product summary", short and concise, in English, understandable for retail investors, and clearly separate from other marketing materials.
- A prominent warning that past performance is not a guide to future performance, with the year manufactured, period, currency and source.
- A warning that the product may not be appropriate for investors who plan to withdraw their money within the recommended holding period.
- Complaints details, Financial Ombudsman Service and compensation scheme position, and the fund's authorisation status.
- Why costs matter, that the seller may charge more, and which figures are estimates.
- Reviewed at least every 12 months, and after a material change to the objective or strategy or market events that materially alter the risk and return information; each version kept for at least 3 years, and the risk score calculation for 5 years. A small change in volatility that moves the score to a neighbouring band does not by itself require an update before the annual review.
Request both PDFs
Tell us who you are and we will show you the Essential and Enhanced examples straight away.
How this sample was built
The fund and its figures are fictitious, but the summary was produced exactly as a client's would be: ten years of weekly prices, costs and product details went in on our CCI template, and the engine calculated the risk score, the costs in pounds and the £10,000 performance graph, cross-checked them and wrote both versions with a rule checklist alongside.
What changes for your fund
- Your branding and your choice of Essential or Enhanced
- Your share classes, each with its own score, costs and graph
- Simulated history for any share class without ten years of prices
- Your answers to the risk questions, recorded in the risk score record
- Annual reviews and material-change updates handled for you
Related
Sources: FCA PS25/20, FCA Handbook DISC 3, DISC 4.1, DISC 5.4, DISC 6, DISC 7.2, COBS 4.15, Simmons & Simmons client update. Last reviewed 6 October 2026.